An affordable housing cooperative is a form of community ownership in which residents collectively own and democratically control the building or development they live in. Instead of paying rent to a landlord or holding an individual mortgage on a single unit, members of a housing cooperative buy a share in a nonprofit corporation that owns the entire property. That share gives them the right to occupy a home and a vote in how the community is run. The result is a model that keeps housing permanently affordable, builds wealth for people who have historically been locked out of ownership, and puts decision-making power in the hands of the people who actually live there.
This guide explains what a housing cooperative is, how it differs from renting and traditional homeownership, the main types of co-ops, how they stay affordable over time, and what it takes to join or start one.
How a Housing Cooperative Works
In a housing cooperative, the property is owned by a cooperative corporation. When you join, you do not buy a deed to a specific apartment. You purchase a membership share in the corporation, and that share comes with a proprietary lease (sometimes called an occupancy agreement) granting you exclusive use of a particular unit.
Each household typically gets one vote, regardless of how large their unit is or how much they paid for their share. Members elect a board of directors from among themselves, and that board makes decisions about budgets, maintenance, rules, and long-term planning — often with input from the full membership at regular meetings.
Members pay a monthly fee, frequently called a carrying charge, that covers the cooperative's blanket mortgage, property taxes, insurance, utilities, maintenance, and reserves. Because the co-op operates on a not-for-profit or limited-profit basis, those charges are set to cover real costs rather than to generate returns for an outside owner. There is no landlord extracting profit, which is one of the structural reasons co-ops can remain affordable.
Ownership without a landlord
The defining feature of cooperative housing is that residents are both the owners and the occupants. This collective ownership structure changes the incentives. Maintenance decisions, rule changes, and budgets are made by and for the people who live with the consequences. Members build equity and stability while sharing responsibility for the building's upkeep and governance.
Types of Housing Cooperatives
Not all co-ops are the same. The differences mostly come down to how much equity a member can build and how the resale price of a share is set. These rules determine whether a cooperative stays affordable for the next generation of members.
Limited-equity cooperatives (LECs)
A limited-equity cooperative is the model most closely associated with affordable housing. Resale prices for shares are capped by a formula written into the co-op's bylaws — often tied to the original purchase price plus a modest, regulated increase that may track inflation or a set percentage. This cap is the mechanism that keeps the housing affordable: members can build some equity and recover their investment when they leave, but they cannot sell their share at full market value. That trade-off ensures the home remains within reach for the next moderate- or low-income household.
Limited-equity cooperatives are commonly used in subsidized and mission-driven developments, and they are the structure most often supported by public funding, community land trusts, and nonprofit developers.
Market-rate cooperatives
In a market-rate cooperative, members can sell their shares for whatever the market will bear, much like selling a condominium. These co-ops can build significant individual wealth but do not preserve long-term affordability, since share prices rise with the market. Many older co-ops in high-cost cities are market-rate.
Zero-equity (or leasing) cooperatives
In a zero-equity cooperative, members do not build equity in their shares at all. They pay a low or nominal buy-in and benefit from democratic control, stable carrying charges, and protection from displacement, but they cannot sell a share for a gain. This model maximizes affordability and is often used in deeply subsidized or rental-conversion projects.
How Co-ops Stay Affordable
Affordability in a housing cooperative is not an accident — it is engineered into the legal structure. Several mechanisms work together:
- Resale restrictions. Limited- and zero-equity formulas cap how much a departing member can charge, keeping shares affordable in perpetuity.
- No landlord profit. Carrying charges cover actual operating costs and reserves, not investor returns.
- Blanket financing. The co-op holds a single mortgage on the whole property, which can be easier and cheaper to finance than dozens of individual unit loans.
- Collective purchasing power. Bulk contracts for utilities, insurance, and maintenance reduce per-unit costs.
- Public and mission-driven subsidy. Grants, low-interest loans, tax abatements, and partnerships with community land trusts or nonprofit developers lower the cost of entry and operation.
Because these protections live in the bylaws and proprietary lease rather than depending on any one owner's goodwill, affordability persists across decades and ownership changes.
Cooperative Housing vs. Renting vs. Condos
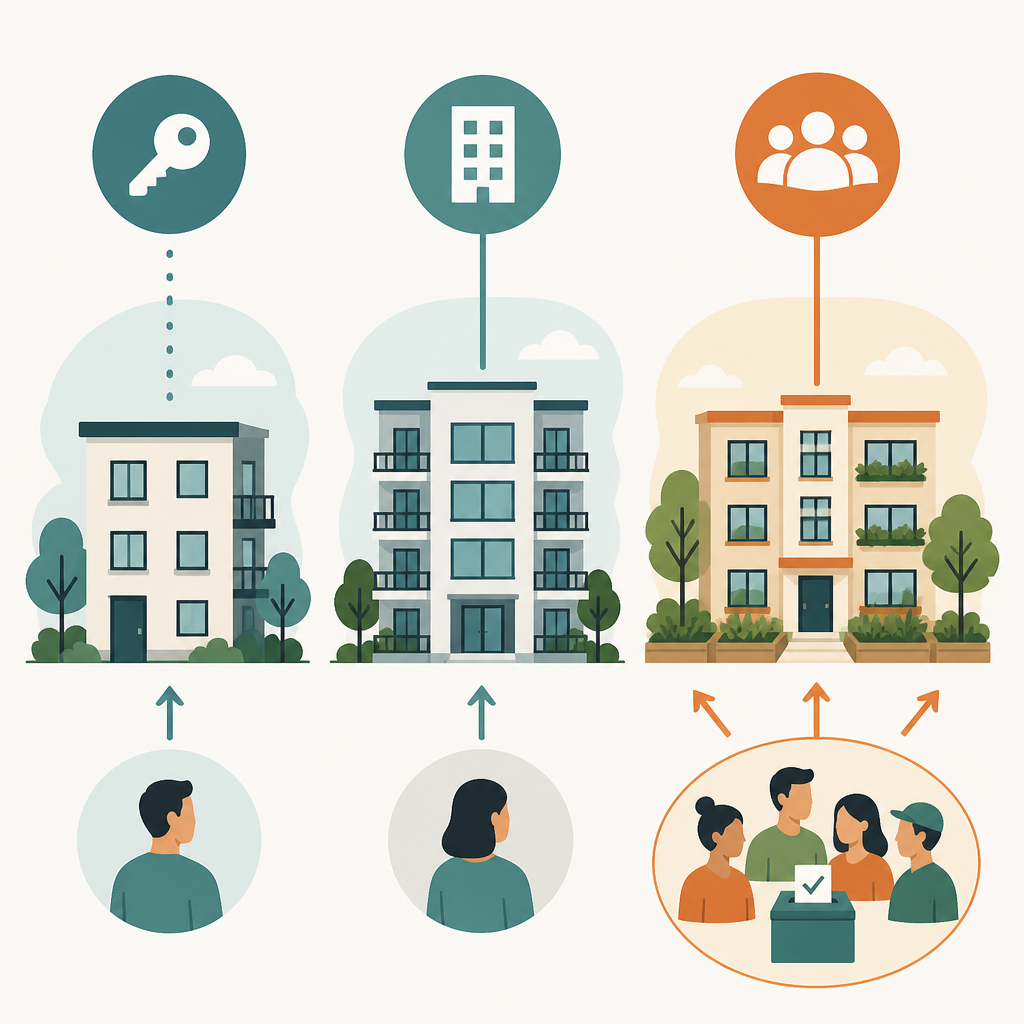
It helps to see the affordable housing cooperative alongside the two models most people already know.
| Feature | Renting | Condominium | Housing Cooperative |
|---|---|---|---|
| What you own | Nothing | Your individual unit + share of common areas | A share in the corporation that owns everything |
| Monthly payment | Rent to landlord | Mortgage + HOA fees | Carrying charge (covers mortgage, taxes, operations) |
| Control over decisions | None | HOA board vote | One member, one vote |
| Equity / wealth-building | None | Full market appreciation | Depends on co-op type (often limited) |
| Affordability over time | Set by landlord | Market-driven | Can be permanently protected |
The cooperative sits between renting and full ownership. It offers more security, control, and equity than renting, while trading away some of the speculative upside of condo ownership in exchange for lasting affordability and community governance.
Benefits and Trade-offs
Benefits
- Stability and security. Members are protected from arbitrary rent increases and from displacement when a building is sold.
- Wealth-building for excluded households. Even limited equity is a meaningful asset for families who have never had access to homeownership.
- Democratic control. Residents govern their own community and shape the rules that affect their lives.
- Lower and predictable costs. Carrying charges reflect actual expenses, and collective purchasing reduces them.
- Community and mutual support. Shared ownership tends to build stronger neighbor relationships and collective accountability.
Trade-offs
- Limited resale value in limited- and zero-equity models.
- Shared responsibility. Governance and maintenance require participation; members must show up for meetings and decisions.
- Financing can be harder. Share loans and co-op mortgages are less common than conventional home loans, though that is changing.
- Approval to join. Co-ops typically vet prospective members, which protects the community but adds a step.
Why Affordable Housing Cooperatives Matter Now
Housing cooperatives already support roughly 1.5 million families across the United States, and policy momentum is growing. In June 2026, Congress passed the 21st Century ROAD to Housing Act (H.R. 6644, 119th Congress), now law as of July 2026 — described as the most significant housing affordability law since 1990. Provisions championed by Representative Nydia Velázquez explicitly authorize housing cooperatives as eligible participants in federal housing programs.
That recognition matters. For years, cooperatives operated at the margins of federal housing policy, often having to retrofit themselves into programs designed for rentals or single-family ownership. Explicitly naming co-ops as eligible participants validates the model and opens doors to financing and support that make it easier to launch and sustain affordable cooperatives in disinvested communities. It signals that community ownership is being treated as a serious, scalable tool for the affordability crisis — not a niche experiment.
How Built By DAO + Blueprint Fit In
Built By DAO is a venture studio building tools and capital structures for community-owned development. Our cooperative housing arm, Urban Array, deploys the affordable housing cooperative model directly in disinvested communities — turning the concepts in this guide into real buildings owned by the people who live in them.
The hard part of starting a co-op has always been the operational complexity: structuring the corporation, modeling carrying charges, assembling financing, navigating subsidy programs, and onboarding members. That is exactly what our flagship platform, Blueprint, is built to solve. Blueprint is software to plan, finance, and launch affordable housing cooperatives — giving developers, community groups, and resident organizers a guided path from idea to occupancy.
With cooperatives now explicitly recognized in federal housing law, the timing has never been better to build one. Blueprint helps you operationalize the model the 21st Century ROAD to Housing Act validates.
Ready to plan, finance, and launch an affordable housing cooperative? Get started with Blueprint.
Frequently Asked Questions
What is the difference between a co-op and a condo?
In a condominium, you own your individual unit outright and hold a deed to it. In a housing cooperative, you own a share in the corporation that owns the entire property, and that share gives you the right to occupy a unit. Condos appreciate at market rates; many co-ops — especially limited-equity cooperatives — cap resale prices to stay affordable.
Can you build equity in an affordable housing cooperative?
Yes, but it depends on the type. Market-rate co-ops allow full market appreciation. Limited-equity cooperatives let you build modest, capped equity. Zero-equity cooperatives offer little or no equity gain but maximize affordability and stability. Even limited equity can be a meaningful first asset for households new to ownership.
How do you join a housing cooperative?
You purchase a membership share and are typically approved by the co-op's board or membership committee, which may review your income, references, and willingness to participate in governance. Limited-equity co-ops often have income eligibility requirements tied to their affordability mission. Some co-ops maintain waiting lists.
Are housing cooperatives a good investment?
If your goal is maximum financial return, a limited-equity co-op is not designed for that — its value lies in affordability, stability, and democratic control. If your goal is secure, affordable housing with some equity, lower predictable costs, and protection from displacement, a cooperative can be an excellent choice. Market-rate co-ops behave more like traditional real estate investments.
How are housing cooperatives financed?
The cooperative corporation usually holds a single blanket mortgage on the entire property. Individual members may take out a share loan to finance their buy-in. Affordable co-ops also draw on grants, low-interest public loans, tax abatements, and partnerships with nonprofits, community land trusts, and — increasingly — federal housing programs that now explicitly include cooperatives.
What does the 21st Century ROAD to Housing Act mean for co-ops?
Passed in June 2026 and law since that July, the act includes provisions that explicitly authorize housing cooperatives as eligible participants in federal housing programs. This federal recognition makes it easier for co-ops to access financing and support, validating community ownership as a mainstream tool for tackling the affordability crisis.