A cooperative resale equity formula is the rule that decides how much a departing member gets paid when they leave a limited-equity housing cooperative. It is the single most important provision in any shared-equity housing model, because it sets the balance between two goals that pull against each other: keeping the home permanently affordable for the next household, and letting the current household build some wealth while they live there. Get the formula right and a co-op stays affordable for generations while still rewarding members. Get it wrong and the home either prices out the next family or strands members with nothing.
This guide explains the main resale formula types used in limited-equity cooperatives and shared-equity housing, walks through clearly hypothetical worked examples, and lays out the affordability-versus-wealth-building tradeoff in plain terms. All numbers below are invented for illustration. They are not market data and should not be used to model a real project.
What "limited equity" actually means
In a conventional home purchase, you own the property outright (subject to your mortgage) and capture 100% of any appreciation when you sell. In a limited-equity cooperative, you do not own a unit. You own a share in a cooperative corporation that owns the whole building, and that share gives you the exclusive right to occupy your unit under a proprietary lease.
The "limited" part is a contractual cap on how much your share can appreciate. When you joined, you paid a share price (sometimes called the carrying value or transfer value). When you leave, the co-op's bylaws or a regulatory agreement dictate the maximum price you can sell your share for. That ceiling is the resale formula. Because the formula holds the share price well below open-market appreciation, the next buyer can afford to join. The discount you accept on the way out is what funds the affordability the next household enjoys on the way in.
Shared-equity housing is the broader family this belongs to. It includes limited-equity co-ops, community land trust (CLT) homes, and deed-restricted ownership. They differ in legal structure but share the same engine: a formula that limits resale price in exchange for long-term affordability.
The five common resale formula types
There is no single standard formula. Most programs use one of five approaches, or a blend. Each makes a different choice about how much appreciation a member keeps.
1. Appraisal-based formula
The member's equity is tied to a percentage of the change in the home's appraised market value. The co-op orders an appraisal at purchase and another at sale, and the member receives their original investment plus an agreed share, often 25% to 35%, of the appraised gain.
Hypothetical example. Maria buys a co-op share for an initial equity contribution of $20,000. The unit appraises at $200,000 at purchase. Seven years later it appraises at $260,000, a $60,000 gain. Her bylaws grant members 25% of appraised appreciation.
- Member's share of appreciation: 25% of $60,000 = $15,000
- Resale equity: $20,000 + $15,000 = $35,000
The co-op retains the other $45,000 of appreciation as a subsidy that keeps the next share price affordable. Appraisal-based formulas track the real market most closely, which is also their weakness: in a hot market the member's payout can climb faster than local incomes, slowly eroding affordability.
2. Indexed formula (AMI or CPI)
Instead of an appraisal, the share price grows by an external index, most often Area Median Income (AMI) or the Consumer Price Index (CPI). AMI indexing is popular because it ties resale price directly to what local households can actually afford to pay.
Hypothetical example (AMI-indexed). James buys a share for $25,000. At purchase, his metro's AMI is $80,000. Six years later AMI has risen to $92,000, an increase of 15%.
- Indexed equity: $25,000 x (92,000 / 80,000) = $25,000 x 1.15 = $28,750
His equity grew by $3,750, in lockstep with local incomes. CPI indexing works identically but uses inflation instead of income. If CPI rose 18% over the same period, the resale value would be $25,000 x 1.18 = $29,500. AMI indexing is generally considered the strongest guarantee of durable affordability, because the price can never outrun the purchasing power of the income tier the co-op serves.
3. Fixed-rate (flat appreciation) formula
The share appreciates by a fixed percentage each year, set in the bylaws and entirely independent of the market. A typical figure might be 1% to 3% per year, sometimes simple, sometimes compounded.
Hypothetical example (compounded at 2%). Aisha buys a share for $30,000 and stays eight years.
- Resale equity: $30,000 x (1.02)^8 = $30,000 x 1.1717 = $35,151
Fixed-rate formulas are the simplest to administer and the most predictable for both members and lenders. Their risk runs in two directions: in a high-inflation stretch a 2% cap can leave members behind, while in a flat market it can drift above what the next buyer can afford. Choosing the rate is the entire ballgame.
4. Mortgage-based (amortization) formula
Member equity is defined largely by how much principal they have paid down, plus their original down payment, plus any limited appreciation allowance. This mirrors how equity accrues in conventional ownership, where early payments are mostly interest and equity builds slowly, then accelerates.
Hypothetical example. Devon contributes a $15,000 share down payment and carries a share loan. Over ten years he pays down $22,000 of principal. His bylaws add a flat 1%-per-year appreciation allowance on the original $150,000 unit value, roughly $15,000 over the period.
- Resale equity: $15,000 down payment + $22,000 principal paid + $15,000 appreciation allowance = $52,000
Mortgage-based formulas reward members who stay long enough to amortize, which encourages stability, but they can disadvantage members who must leave early before meaningful principal has been paid.
5. Improvements credits
This is not a standalone formula so much as an add-on that most programs layer on top of the others. When a member makes durable, value-adding capital improvements, such as a new furnace, updated kitchen, or accessibility modifications, an improvements credit reimburses some or all of the documented, pre-approved cost at resale. The point is fairness: a member should not lose money for upgrades that benefit the next household.
Hypothetical example. Return to Maria's appraisal-based payout of $35,000. During year five she installed an approved $8,000 high-efficiency heating system. Her bylaws credit 100% of approved improvements, depreciated 10% per year.
- Two years of depreciation: $8,000 x (1 - 0.20) = $6,400 credit
- Total resale equity: $35,000 + $6,400 = $41,400
Most programs require pre-approval and receipts, exclude cosmetic or personal-taste items, and depreciate the credit over time so it reflects remaining useful life rather than original cost.
The affordability versus wealth-building tradeoff
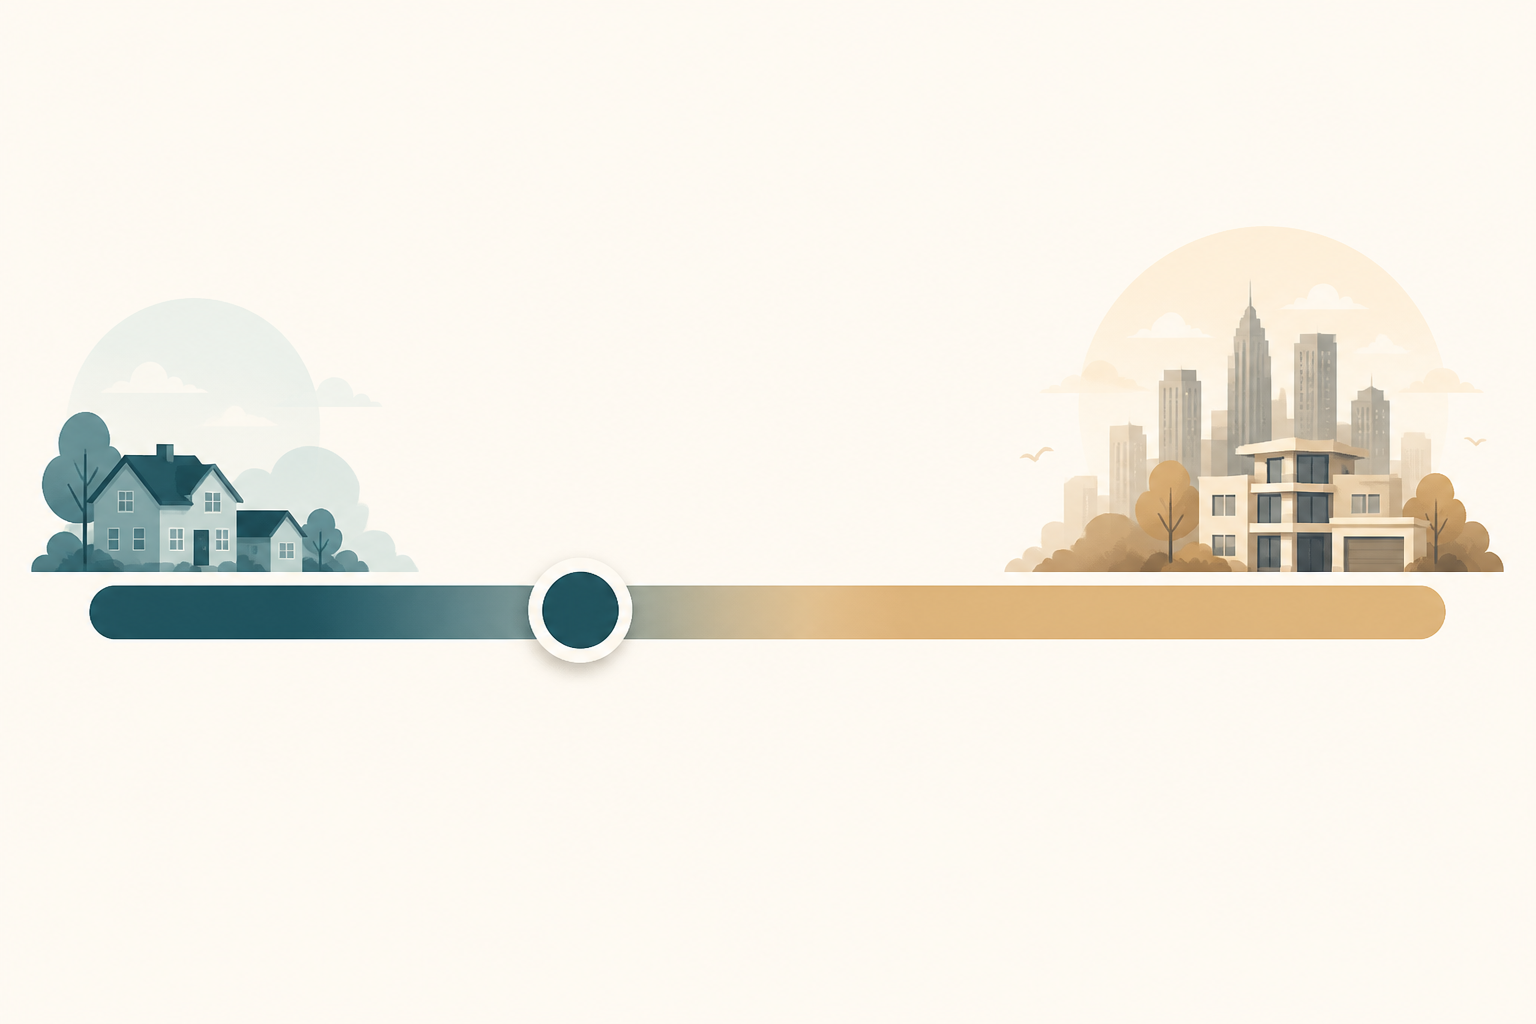
Every formula above is a single dial set somewhere on a spectrum. At one end is maximum affordability: the share price barely moves, the home stays cheap forever, and members build little wealth. At the other end is maximum wealth-building: members capture most appreciation, build real assets, and the home gradually becomes unaffordable to the next buyer, defeating the model's purpose.
Limited-equity cooperatives deliberately sit toward the affordability end, but not at the extreme. The design goal is usually framed as modest, reliable equity: members should leave with more than they put in, ideally enough to seed a down payment elsewhere, while the home remains affordable to a household at the same income tier they entered at.
This tradeoff deserves honesty rather than spin. A limited-equity co-op is not a wealth-building vehicle comparable to market-rate ownership. A member who buys a $25,000 share and leaves with $35,000 has gained $10,000, not the six-figure appreciation a market-rate owner might capture in the same market and period. What the member receives in exchange is lower monthly carrying costs, security of tenure, protection from speculation and displacement, democratic control over their housing, and a guaranteed, predictable exit value. For households who would otherwise rent indefinitely with zero equity, that is a meaningful gain. For households expecting market-rate returns, it is the wrong product, and good programs say so up front.
A few design levers shape where a given co-op lands:
- Index choice. AMI indexing protects affordability most reliably. CPI can outpace local incomes in some markets. Appraisal-based capture leans furthest toward wealth-building.
- Appreciation share. A higher member percentage of appraised gain shifts toward wealth-building and away from durable affordability.
- Improvements policy. Generous, well-documented credits keep the formula fair without undermining affordability, because they reimburse cost rather than reward speculation.
- Holding-period rules. Some programs phase in equity to discourage quick flips and reward stability.
Why the policy context matters now
Resale formulas have lived mostly in state and local programs and nonprofit bylaws. That footprint is widening. The 21st Century ROAD to Housing Act (H.R.6644), passed by Congress in June 2026 (now law as of July 2026), includes the Velázquez provisions that authorize cooperatives within federal housing programs. By recognizing co-ops as eligible structures, those provisions open a path for shared-equity ownership, building on the roughly 1.5 million families already living in cooperative housing, to scale through federal channels that were previously hard for co-ops to access.
What does that mean for formulas? Federal participation typically brings standardization. Programs operating with federal recognition will need resale formulas that are transparent, auditable, and consistent enough to satisfy lenders, regulators, and oversight bodies, while still preserving the local flexibility that makes co-ops work. The formula types in this guide are exactly the building blocks that emerging standards draw from. Co-ops that document their formula clearly, with worked examples and depreciation schedules, will be best positioned to participate.
How Built By DAO + Blueprint fit in
Built By DAO is a venture studio for community-owned development. Our flagship platform, Blueprint, is software to plan, finance, and launch affordable housing cooperatives, and the resale formula is one of the first things a founding group has to get right.
Blueprint lets organizers model each formula type side by side, AMI- and CPI-indexed, fixed-rate, appraisal-based, and mortgage-based, with improvements credits layered on, so a steering committee can see the long-run affordability and member-equity outcomes before a single bylaw is adopted. You can stress-test how a 2% fixed rate behaves over twenty years, compare it against AMI indexing in your actual metro, and generate the worked examples your members and lenders will need to understand the deal. As federal pathways open under the ROAD to Housing Act, having a clear, defensible formula is no longer optional.
Ready to model your co-op's resale formula? Start with Blueprint at blueprint.builtbydao.com and turn the tradeoff between affordability and equity into a decision you can see, compare, and defend.
Frequently Asked Questions
What is a cooperative resale equity formula?
It is the rule in a limited-equity cooperative's bylaws or regulatory agreement that caps how much a member can sell their share for when they leave. It determines the member's payout and, by holding the price below market, keeps the unit affordable for the next household. Common types include appraisal-based, AMI- or CPI-indexed, fixed-rate, and mortgage-based formulas, often combined with improvements credits.
Do members in a limited-equity co-op build any wealth?
Yes, but modestly and by design. Members typically leave with more than their original investment, enough to provide a real, predictable nest egg, but far less than the appreciation a market-rate owner might capture. The tradeoff is deliberate: lower monthly costs, security of tenure, and durable affordability for the next family in exchange for capped appreciation.
Which formula best protects long-term affordability?
AMI (Area Median Income) indexing is widely viewed as the strongest protection, because resale price rises only as fast as local incomes, so the home can never outpace what its target income tier can afford. Fixed-rate formulas are simplest and most predictable but require carefully choosing the rate. Appraisal-based formulas track the market most closely and therefore protect affordability the least.
How do improvements credits work?
When a member makes durable, value-adding upgrades, such as a new furnace or accessibility modifications, the co-op reimburses some or all of the documented, pre-approved cost at resale, usually depreciated over time. The goal is fairness, so members are not penalized for improvements that benefit the next household. Most programs require pre-approval and receipts and exclude cosmetic items.
How does the ROAD to Housing Act affect co-op resale formulas?
The 21st Century ROAD to Housing Act (H.R.6644), passed by Congress in June 2026, includes Velázquez provisions authorizing cooperatives within federal housing programs, building on the roughly 1.5 million families already living in cooperative housing. Federal participation tends to encourage transparent, standardized, auditable resale formulas, which is why clearly documented formula types and worked examples are increasingly important.
Are the numbers in this guide real?
No. Every figure in this guide is hypothetical and chosen only to illustrate how each formula works. They are not market data and should not be used to model a real project. Use software like Blueprint with your own local inputs to produce accurate projections.