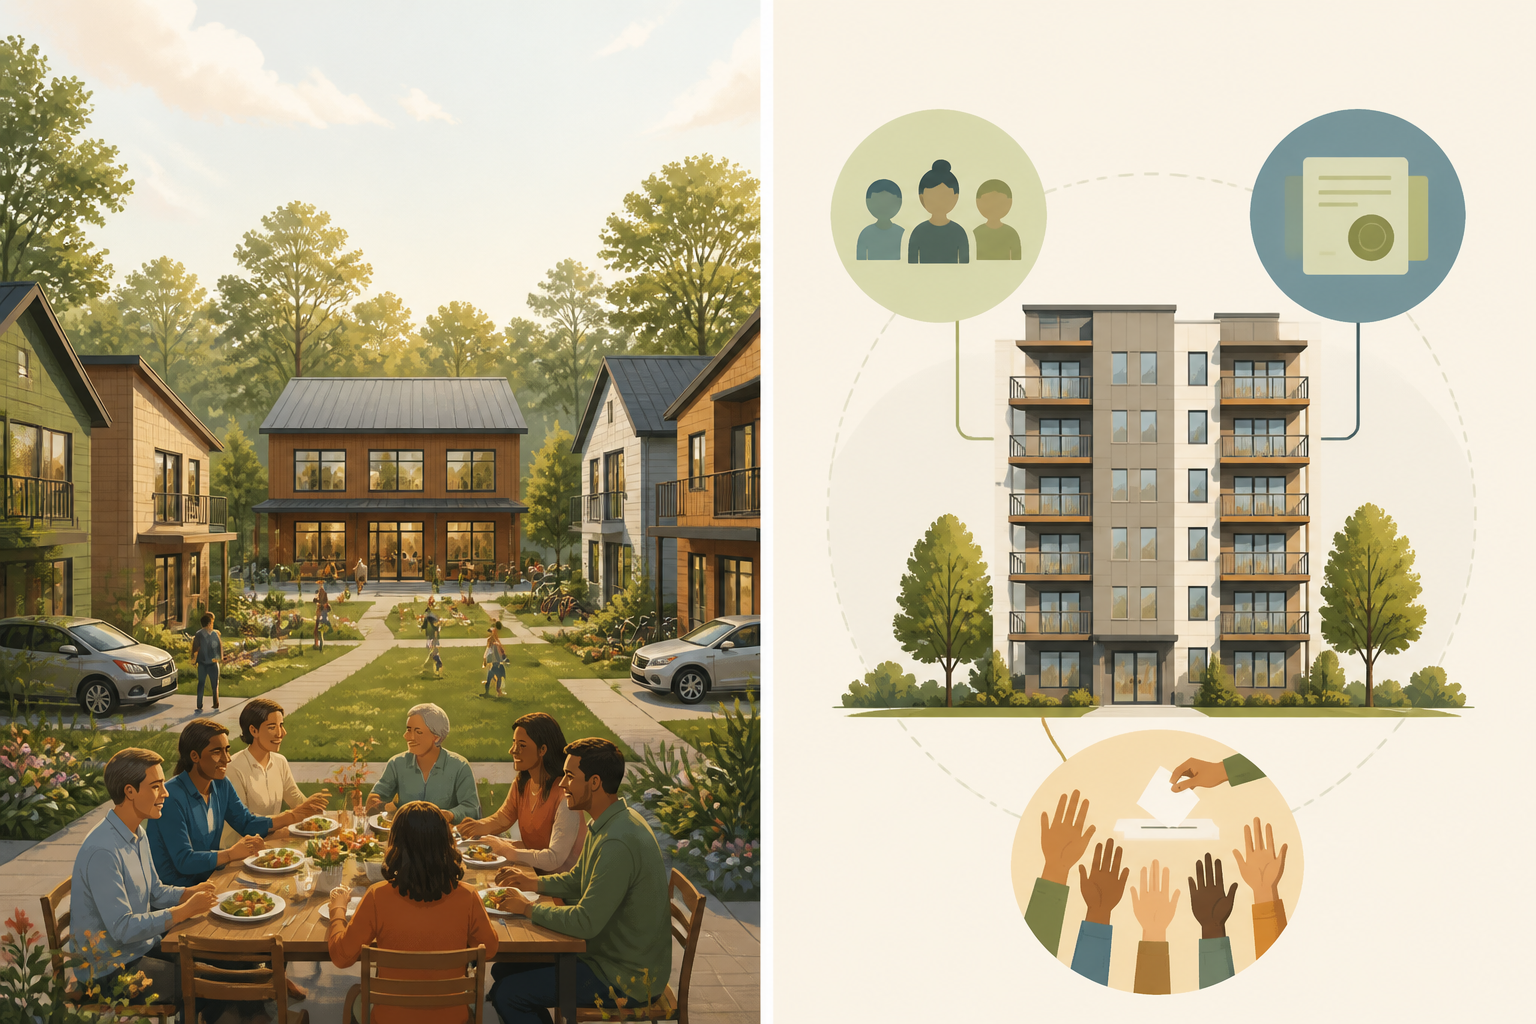
If you are weighing cohousing vs housing cooperative as a path to more connected, more affordable living, you are really asking two different questions at once: how do you want to own your home, and how do you want to live alongside your neighbors. The two models are often lumped together because both reject the isolated, owner-occupied single-family default. But they solve different problems. Cohousing is primarily a design-and-governance philosophy about how a neighborhood is laid out and run. A housing cooperative is primarily a legal-and-financial structure about how property is owned and money flows. Understanding that distinction is the difference between choosing a label and choosing a model that actually fits your community.
This guide breaks down both models across ownership, financing, governance, affordability, and resale — and explains why the policy environment for cooperatives changed meaningfully in 2026.
What Is Cohousing?
Cohousing describes an intentional neighborhood designed around community interaction. The hallmark is physical layout: private homes clustered to encourage daily contact, cars pushed to the perimeter, and a shared "common house" with a large kitchen, dining area, and spaces for meetings, guests, laundry, or childcare. Residents typically share regular common meals and participate in managing the community.
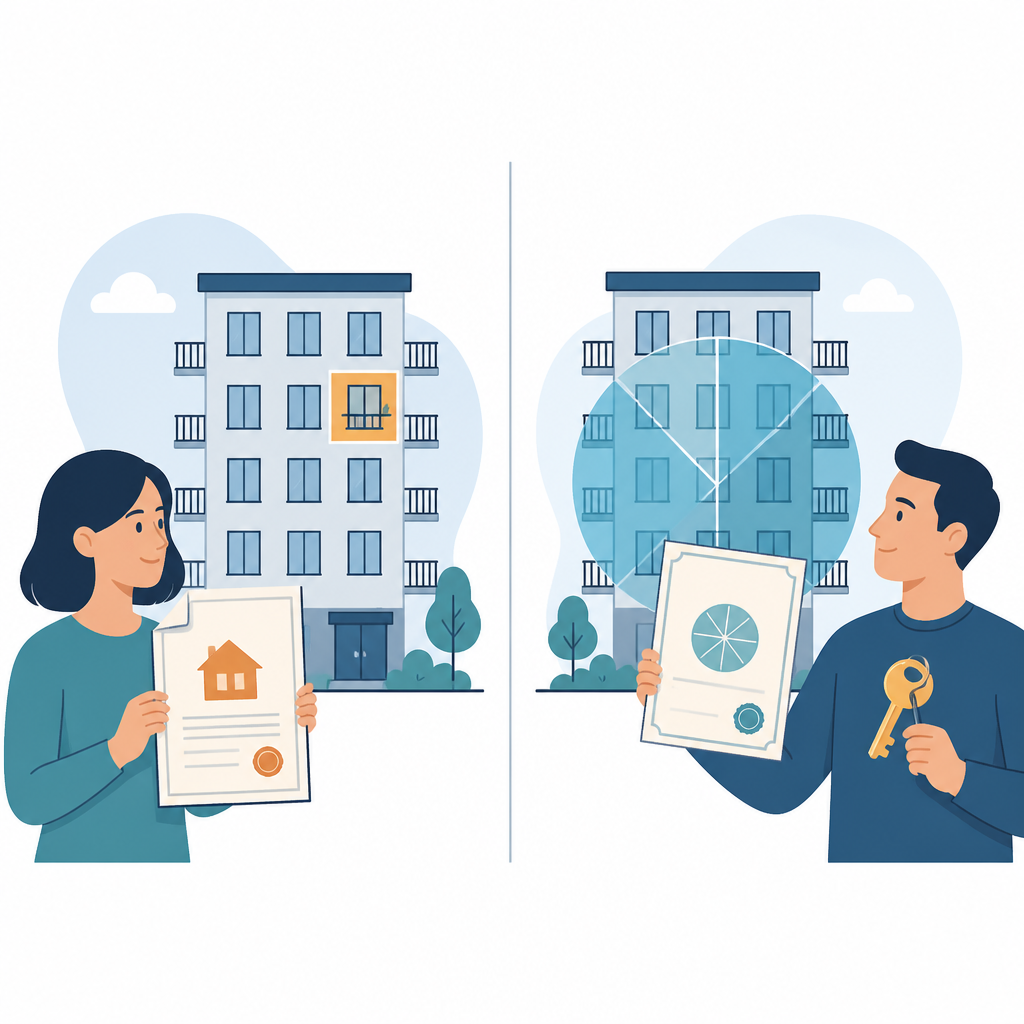
What cohousing usually does not dictate is the underlying ownership structure. Most cohousing communities in the United States are organized as condominiums, where each household holds title to its own unit plus an undivided interest in common areas. Others use homeowner associations or, less commonly, a cooperative. In other words, cohousing answers "how is the neighborhood designed and governed day to day?" — not "who owns the building?"
The core ideas of cohousing are usually traced to Danish bofællesskab developments of the 1960s and 1970s, popularized in North America in the late 1980s. The model emphasizes participatory design, where future residents help plan the community, and consensus-oriented self-governance.
What Is a Housing Cooperative?
A housing cooperative is a legal corporation that owns real estate. Instead of buying a unit, you buy a membership share in the corporation, and that share grants you a long-term proprietary lease to occupy a specific home. You are simultaneously a part-owner of the whole entity and a tenant of your unit. Decisions are made democratically, typically on a one-member-one-vote basis, regardless of unit size.
Cooperatives come in several flavors, and the differences matter enormously:
Market-Rate Cooperatives
Shares are bought and sold at whatever the market will bear. These are common in cities like New York, where co-op apartments function much like condos financially but with stricter board approval of buyers.
Limited-Equity Cooperatives (LECs)
Resale prices are capped by formula, so the home stays affordable for the next household instead of appreciating to market value. Owners build modest equity but forgo speculative gains. LECs are the workhorse of permanently affordable, community-owned housing.
Zero-Equity / Leasing Cooperatives
Members pay a small or no share price and have no equity stake; the structure functions more like collective, democratically governed rental housing.
The cooperative model is what underpins much of the United States' permanently affordable, community-controlled housing stock — and it is the structure most directly affected by recent federal policy.
Cohousing vs Housing Cooperative: Side-by-Side Comparison
The clearest way to see the contrast is to line the models up across the dimensions that actually shape day-to-day life and long-term finances.
| Dimension | Cohousing | Housing Cooperative |
|---|---|---|
| Primary nature | Design + governance philosophy | Legal + financial ownership structure |
| What you own | Usually your unit (commonly a condo) plus shared common areas | A membership share in a corporation + a proprietary lease to your unit |
| Typical legal form | Condominium or HOA (sometimes a co-op) | Cooperative corporation |
| Financing | Individual mortgage on your unit | Share loan / co-op loan; corporation may carry a blanket mortgage |
| Governance | Participatory, often consensus-based | Democratic, typically one member, one vote |
| Affordability mechanism | Not inherent; depends on market | Can be built in via limited-equity resale caps |
| Resale | Sell your unit at market value | Sell your share — at market or at a capped price (LEC) |
| Shared spaces | Central to the model (common house, shared meals) | Optional; varies by community |
| Best at solving | Social isolation, neighborhood design | Affordability, collective ownership, displacement |
| Can combine? | Yes — a cohousing community can be legally organized as a co-op | Yes — a co-op can adopt cohousing design and culture |
The last row is the most important takeaway: these models are not mutually exclusive. A community can adopt cohousing design principles and organize legal ownership as a limited-equity cooperative, capturing both the social benefits and the affordability protections.
Ownership and Financing: The Real Dividing Line
The financial mechanics are where the models genuinely diverge.
In most cohousing communities organized as condominiums, you take out a conventional individual mortgage on your unit. Your financing looks like any other condo purchase, and your home appreciates (or depreciates) with the local market. That makes financing familiar to lenders but offers no built-in affordability protection.
In a cooperative, you finance a share, not real property directly. Some lenders offer share loans (sometimes called co-op loans) for this purpose. The cooperative corporation itself may carry a single blanket mortgage on the entire property, and your monthly carrying charges cover your portion of that debt, taxes, maintenance, and reserves. This pooled structure can lower per-household costs but historically narrowed the pool of willing lenders and complicated access to federal financing — a gap that 2026 policy began to address.
Governance: Consensus vs. Democratic Vote
Both models reject top-down landlord control, but they get there differently.
Cohousing leans heavily on participatory, consensus-oriented decision-making. Many communities aim for broad agreement rather than majority rule, which can deepen buy-in but also slow decisions.
Cooperatives run on formal democratic governance: members elect a board, and major decisions go to a vote, usually one member, one vote regardless of how large your unit is. This is codified in bylaws and corporate law, giving cooperatives a more standardized, legally enforceable governance backbone — useful when a community needs to qualify for financing, grants, or regulatory programs.
Affordability: Why the Cooperative Model Carries More Weight in 2026
Cohousing does not inherently make housing affordable. Because most communities are market-rate condos, prices track the surrounding market. A cohousing home in an expensive metro will be expensive.
The cooperative model — specifically the limited-equity cooperative — is purpose-built for durable affordability. Resale caps keep homes attainable for successive working-class households rather than letting them appreciate out of reach. This is precisely why cooperatives sit at the center of recent federal housing policy.
In June 2026, the 21st Century ROAD to Housing Act (H.R. 6644) was passed by Congress, widely described as the largest housing affordability law since 1990. Among its provisions are measures championed by Representative Nydia Velázquez that authorize and expand the role of housing cooperatives within federal housing programs — opening doors that the pooled, share-based co-op structure had historically struggled to access. Coverage and program estimates associated with the cooperative provisions point to support reaching on the order of roughly 1.5 million families. (Note: the Act was passed by Congress; readers should confirm the current implementation status of specific provisions, as rulemaking and program rollout follow passage.)
The practical implication: the cooperative path to community-owned, permanently affordable housing now sits on firmer federal footing than it did even a year ago. For communities choosing between models, that materially strengthens the case for a cooperative structure — especially a limited-equity one — when affordability and anti-displacement are the goal.
How to Choose Between the Two
Use this rough decision framework:
- Choose cohousing if your top priority is combating social isolation and shaping a neighborhood around connection, and market-rate ownership is acceptable. You want shared meals, a common house, and participatory governance.
- Choose a housing cooperative if your top priority is affordability, collective ownership, resistance to displacement, or access to programs that favor community ownership. The legal-financial structure is the point.
- Combine both if you want connected design and permanent affordability — design the community around cohousing principles and incorporate it as a limited-equity cooperative.
Many of the strongest community-owned developments do exactly the third thing.
How Built By DAO + Blueprint Fit In
Built By DAO is a venture studio for community-owned development. Through brands like Urban Array, which develops cooperative housing in historically disinvested communities, and the broader ecosystem founded by Marquis Davis, the studio focuses on the structures that make community ownership durable rather than aspirational.
The flagship product is Blueprint — software to plan, finance, and launch affordable housing cooperatives. Where this article maps the conceptual differences between models, Blueprint operationalizes the cooperative path: modeling limited-equity structures, mapping financing including the federal programs reshaped by the 21st Century ROAD to Housing Act, and giving founding groups the tooling to move from "we want to own this together" to a chartered, financeable cooperative.
If your community is leaning toward the cooperative model — or wants to pair cohousing design with limited-equity ownership — Blueprint is built to take you from idea to launch.
Plan, finance, and launch your housing cooperative with Blueprint →
Frequently Asked Questions
Is cohousing the same as a housing cooperative?
No. Cohousing is mainly a neighborhood design and governance philosophy, while a housing cooperative is a legal and financial ownership structure. Most cohousing communities are legally organized as condominiums, not cooperatives — though a single community can use both: cohousing design plus cooperative ownership.
Which model is more affordable?
The cooperative model — particularly the limited-equity cooperative — is the one purpose-built for durable affordability, because resale price caps keep homes attainable for future households. Cohousing has no inherent affordability mechanism; prices typically track the local market.
What is the difference between a limited-equity and a market-rate cooperative?
In a market-rate cooperative, shares sell for whatever the market will bear, so owners can capture appreciation. In a limited-equity cooperative, resale prices are capped by a formula, trading speculative gains for permanent affordability for the next member.
How does the 21st Century ROAD to Housing Act affect cooperatives?
The Act (H.R. 6644), passed by Congress in June 2026 (now law as of July 2026), includes Velázquez-championed provisions that authorize and expand the role of housing cooperatives within federal housing programs, with cooperative-related measures aimed at a cooperative sector already home to roughly 1.5 million families. It strengthened the federal footing for the cooperative path to affordable housing.
Can a community be both cohousing and a cooperative at the same time?
Yes. The models address different layers — design/culture versus legal ownership — so a community can adopt cohousing's shared spaces and participatory governance while incorporating as a limited-equity cooperative for affordability. This combination is increasingly common.
Do I get a normal mortgage in a housing cooperative?
Not exactly. You finance a membership share, often through a specialized share loan, rather than a conventional mortgage on real property. The cooperative corporation itself may hold a blanket mortgage on the whole building, with your carrying charges covering your portion.